Cash Advance: Get 250 Fast

Screenshots
Details
- Rating
- 984.00 reviews
- Version
- 1.2.2
- Developer
- KOMPANIIA LORENS PP
Analysis by Norviv
Cash Advance: Get 250 Fast is a finance app from KOMPANIIA LORENS PP that is aimed at people looking for a short-term cash advance. I approached it less like a casual download and more like a tool that could affect a real household budget, because borrowing apps deserve a closer look than ordinary utilities. My first impression was that the app’s appeal is its directness: it focuses on getting a user through a borrowing request rather than surrounding the experience with unrelated financial features.
The app is free to install and is rated for Everyone, but that should not be confused with borrowing being suitable for everyone. A finance application can be simple to open while the decision behind using it remains serious. I would treat this as a possible emergency option, not as extra spending money. The most important question is not whether the application is easy to reach; it is whether the repayment terms, eligibility requirements, and total cost fit comfortably into the user’s next budget.
What the app feels like to use when money is tight
The central experience is built around a cash advance request. That makes the app most relevant in a narrow situation: a necessary expense arrives before payday, and the user needs to understand whether a short-term advance is available. I can see why that straightforward purpose may appeal to someone who does not want to manage investments, track every purchase, or open a full banking platform just to investigate a small borrowing need.
In a realistic everyday scenario, imagine a household facing an urgent transport repair shortly before income arrives. A sensible workflow would be to open the app, review the request process, check every cost and repayment condition shown before accepting anything, and compare the result with alternatives such as asking the provider for more time or using an existing bank facility. The useful part of the app is the possibility of handling that initial inquiry in one place. The risky part is moving too quickly simply because the request feels convenient.
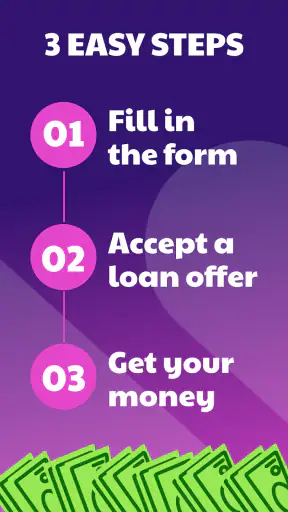
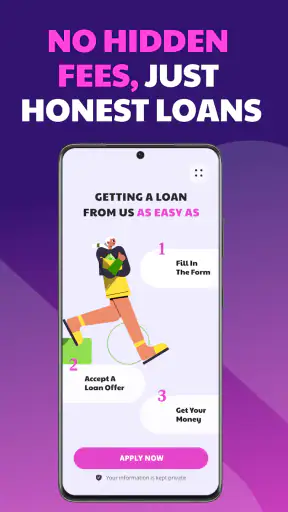
The store summary emphasizes simple steps and no subscription fees. I see that as a helpful distinction from apps that charge for ongoing access, but it does not answer the questions that matter most for a loan: whether an advance is approved, how much the user will repay, when repayment is due, and whether any other charges apply. Those details should be treated as decision points, not as small print to skim past.
Its current version is 1.2.2, and the app runs on Android devices using version 7.0 or later. That broad compatibility is useful for people with older phones, especially if replacing a device is not realistic during a financial emergency. At the same time, an older operating system may have different security and privacy controls from a recent phone, so I would keep the device updated where possible and avoid using public Wi-Fi while entering sensitive financial information.
A strong starting point, but not a substitute for comparison
Cash Advance: Get 250 Fast has attracted over one hundred thousand installs and a 4.7 average from around twenty-five thousand ratings. Those figures suggest that many people have found the app worth trying, but popularity does not establish that a particular advance is affordable for me or for you. Ratings can describe ease of use while saying little about repayment pressure, approval outcomes, or how a user’s circumstances changed afterward.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would therefore compare the app with three familiar alternatives before accepting an offer. A bank overdraft or existing credit line may have clearer terms for an established customer. An employer advance or a direct payment arrangement with a bill provider may avoid taking on a separate short-term obligation. A local credit union or community lending service may take longer to arrange but could be more appropriate for a recurring need. The app is most compelling when speed and a simple application path matter, not when the user needs a long repayment period or repeated access to credit.
One practical tip is to calculate the repayment from money that is already expected, rather than from an optimistic future plan. I would write down the next income date, fixed bills, food, transport, and any existing repayments before submitting a request. If the remaining amount is not comfortably larger than the proposed repayment, the app is not solving the problem; it is moving the pressure forward.
Trust begins with visible choices and careful review
For a finance app, trust is not created by a polished screen or a high rating alone. I look for clear moments where the user can understand what is being requested, review information before submission, and stop without accidentally committing to borrowing. The most important control is the ability to pause at the final stage and read the amount received, the amount to be repaid, the due date, and any applicable charges as separate items.
I would also avoid treating a prequalification or preliminary result as guaranteed cash. A request can still depend on eligibility checks, identity information, or other conditions. The app’s purpose may be to guide the user through an advance request, but the user should remain in control of whether to continue after seeing the actual offer. If the screen makes the acceptance button prominent while the cost is difficult to locate, I would slow down and inspect every section before proceeding.
Another useful habit is to save or record the final terms in a private place before accepting. A screenshot may help with personal records, provided it is stored securely and does not expose sensitive information through automatic photo backups. I would not rely on memory for a borrowing agreement, especially when the request is made under time pressure.
The developer is listed as KOMPANIIA LORENS PP. That identifies who publishes the app, but it is not by itself a reason to share more information than necessary. I would check the developer name, the app’s privacy disclosures, and the permissions or prompts shown during setup. If the app asks for access that does not appear relevant to a cash advance request, I would decline it or stop until I understood why it was needed.
Handling personal information at the most sensitive moments
A cash advance application naturally involves sensitive information, so the moments before submission deserve the most attention. I would read each consent screen instead of tapping through it, particularly where the wording concerns identity verification, financial details, communications, or sharing with other parties. The goal is not to reject every request automatically; it is to make sure I understand what I am agreeing to and why it is connected to the service.
I would enter information only inside the official application flow and would not send identity documents or account details through an unexpected message. If a notification or email asked me to provide information outside the app, I would return to the application independently rather than following the message. This is a simple way to reduce the chance of confusing a genuine request with a fraudulent one.
Device-level controls are worth using here. I would enable a screen lock, avoid leaving the app open where others can see it, and review notification previews so financial messages do not appear on a locked screen. On a shared phone, I would be especially careful about saved passwords, autofill, and downloaded documents. These steps are not special features of the app, but they make a meaningful difference when a finance tool is used on an everyday device.
I would also pay attention to whether the app gives a clear way to manage communication preferences and account access. If there is a profile area, I would inspect it for contact details, sign-out controls, and any option to review or update information. I would not assume that uninstalling the app closes an account or cancels an obligation. Those are separate actions, and a user should follow the account or agreement instructions rather than relying on deleting the icon.
Where user agency matters most
The best way to use this app is to make the decision outside the rush of the request screen. Before opening it, decide the maximum amount that would genuinely solve the immediate problem and the maximum repayment that the next budget can absorb. That prevents the available amount from becoming the target. A borrowing limit should be treated as a ceiling, not as a recommendation.
I would also prepare a short checklist before beginning:
- What expense must be covered, and can it be delayed or reduced?
- What exact income will cover the repayment?
- What is the total amount to repay rather than only the amount received?
- What happens if the repayment date arrives alongside another essential bill?
- Can I explain the agreement clearly to myself before accepting it?
This checklist gives the user a useful stop point. If the answer to the final question is no, I would not continue until the terms were clear. If the app does not present the relevant information in an understandable way, I would choose a different route, even if that route is slower.
A less obvious trade-off is the difference between convenience and repeat dependence. A fast advance may be reasonable for an isolated timing problem, but using one to cover ordinary recurring expenses can create a cycle in which the next payday is already committed. I would not install the app with the plan of using it every month. If the same shortfall keeps returning, a budget review, bill negotiation, income adjustment, or longer-term debt support is more appropriate.
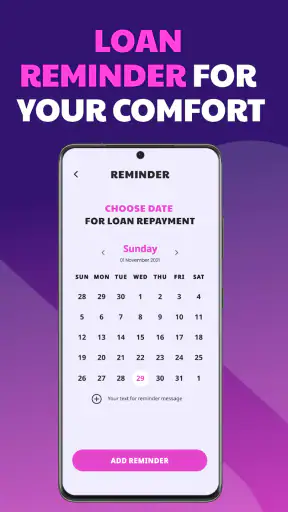
Another practical safeguard is to set a personal reminder several days before the repayment date. The reminder should be based on the agreement, not on a notification that may be missed or delayed. I would keep enough money available for the repayment before spending on optional items, and I would contact the relevant provider through its official support route if a genuine problem arose. Ignoring an obligation because the app is no longer installed would only make the situation harder.
Who will benefit, and who should look elsewhere
I think the app is best suited to an adult who needs to investigate a short-term advance, can verify the terms independently, and already knows how repayment will fit into the next budget. Its free entry point and focused purpose may be useful for someone who wants to explore an option without paying a subscription merely to access the application.
I would be cautious about recommending it to someone who is already behind on several bills, has uncertain income, or needs borrowing to cover basic living costs repeatedly. It is also not the right choice for a person who wants detailed budgeting, savings goals, transaction categorization, or broader financial planning. Those needs are better served by a banking app, budgeting tool, debt adviser, or credit provider designed for a longer relationship.
Someone who values maximum transparency should compare the complete cost and repayment structure with an existing financial provider before accepting anything. The app may be faster than visiting a branch or arranging a conventional product, but speed is not automatically value. A slower option with a more familiar agreement can be the better decision when the amount is significant relative to monthly income.
My cautious verdict after looking beyond the quick request
Cash Advance: Get 250 Fast is a focused finance app rather than a complete money-management service. I like the simplicity of its purpose, the absence of a subscription charge, and the fact that it can be considered on older Android devices. The strong user rating and install base make it a notable option to investigate, but they do not remove the need to examine the individual offer carefully.
My recommendation is conditional: use it as a comparison point for a genuine, short-lived cash gap, not as a routine payday solution. Before sharing sensitive information, review the app’s visible choices, permissions, privacy explanations, and account controls. Before accepting an advance, confirm the total repayment and due date in terms you can explain without guessing.
The safest feature is still the user’s ability to stop before accepting an unaffordable obligation. If the numbers work, the purpose is necessary, and the agreement is clear, the app may fit that narrow situation. If the repayment depends on another loan, an uncertain paycheck, or cutting essentials, I would skip it and look for a more sustainable alternative.
Frequently Asked Questions
01What is Cash Advance: Get 250 Fast, and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help eligible users explore short-term cash advance options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. The app may connect you with third-party lenders or providers, so approval, loan amounts, fees, and terms are not guaranteed.
02Can everyone get a $250 cash advance through the app?
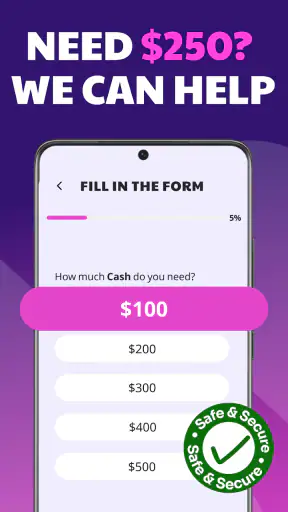
No. The advertised amount should not be understood as a guaranteed payment for every user. Eligibility can depend on factors such as your income, employment status, banking history, identity verification, location, and the requirements of participating providers. Even if you complete the application successfully, you may receive a different amount, a different offer, or no offer at all. Always review the final terms before accepting.
03How quickly can the money arrive after approval?
The app focuses on fast access, but funding speed can vary considerably. Some users may receive money quickly after approval, while others may wait because of bank processing times, verification checks, weekends, holidays, or the policies of the lender or financial provider. Any express-transfer option may involve an additional charge. Check the estimated delivery time and total cost before confirming a request.
04Are there fees, interest, or repayment requirements to consider?
Yes, potential costs and repayment obligations should be reviewed carefully. Depending on the offer, you may encounter service fees, subscription charges, expedited-transfer fees, interest, or other lender costs. Repayment dates and methods can also differ, and a missed payment may lead to additional fees or affect your financial standing. Do not accept an advance until you understand the annual percentage rate, total repayment amount, and due date.
05Is Cash Advance: Get 250 Fast safe to use, and what information does it request?
As with any financial app, use caution before submitting sensitive information. The application may request details such as your name, contact information, identity data, income, employment, and bank-account credentials to process eligibility or connect you with providers. Download it only from an official app store, read its privacy policy, verify the company behind each offer, and avoid sharing passwords or accepting terms you have not fully understood.


